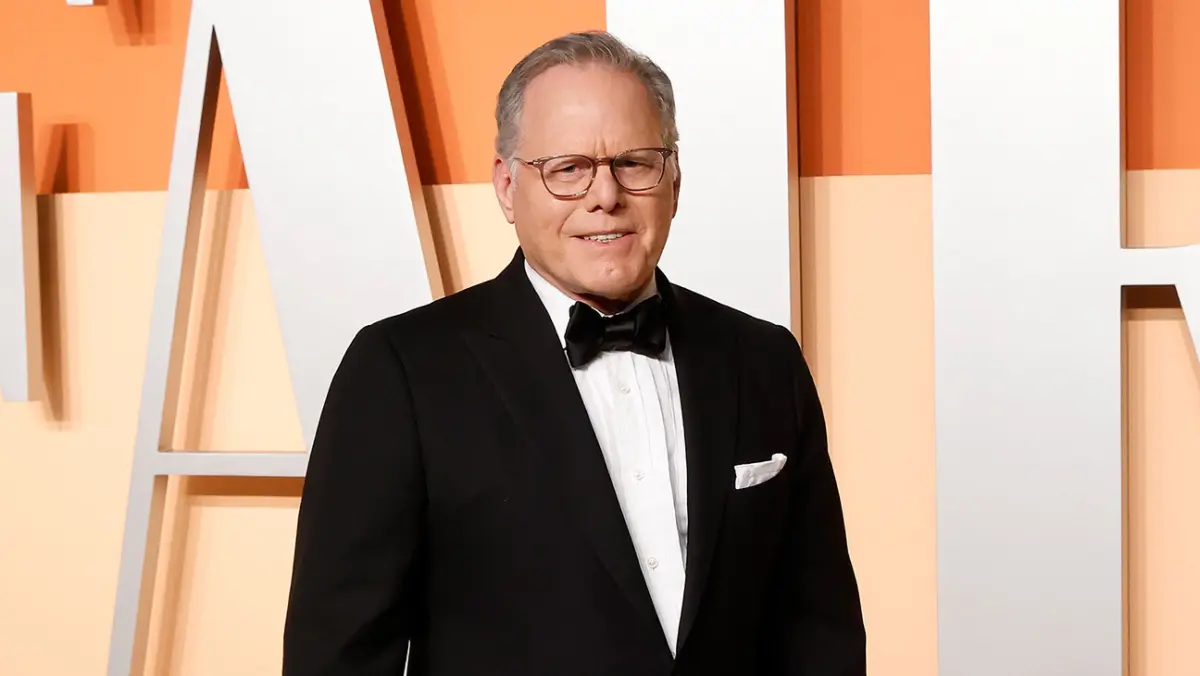
The consolidation of the American media landscape reached a historic zenith this week as the $111 billion takeover of Warner Bros. Discovery (WBD) by the Skydance-led conglomerate officially concluded. Following the finalization of the deal on Tuesday, October 6, former WBD Chief Executive Officer David Zaslav has emerged as one of the transaction’s most significant financial beneficiaries. According to a Form 4 filing submitted to the Securities and Exchange Commission (SEC) on Thursday, Zaslav has realized a total payout exceeding $600 million, a figure derived from the liquidation of his equity holdings and the exercise of vested stock options.
The transaction, which marks one of the largest corporate mergers in the history of the entertainment industry, saw shareholders receive $31 per share plus a supplementary ticking fee. For Zaslav, whose tenure at the helm of WBD was defined by aggressive cost-cutting measures, strategic asset divestitures, and a relentless focus on debt reduction, the payout represents the culmination of his contractual severance provisions and equity vesting schedules.
Anatomy of the Payout: Equity and Options
The SEC documentation provides a granular breakdown of how the $600 million-plus figure was reached. Zaslav liquidated WBD shares valued at approximately $224 million directly linked to the acquisition’s closing. Additionally, the executive held a substantial portfolio of in-the-money stock options that, upon the completion of the merger, netted him an estimated $381 million.
This financial exit is categorized primarily as a severance-related windfall. However, industry analysts note that Zaslav’s compensation package was uniquely structured. Beyond the standard equity and option liquidations, his contract included a highly scrutinized tax reimbursement perk—an unusual provision that has historically sparked debate regarding executive compensation transparency. While the full scope of his total exit package—which includes a cash severance, continued health benefits, and other fringe elements—remains confidential, the disclosed figures alone place him among the highest-paid media executives in the post-merger era.
A Chronology of the Acquisition
The road to this $111 billion merger was marked by months of speculation, regulatory scrutiny, and complex negotiations. The timeline of the Skydance-WBD deal highlights the rapid pace at which the industry has moved to consolidate resources in response to the decline of traditional linear television and the shifting economics of global streaming platforms.
- Early 2024: Whispers of a potential merger between WBD and Skydance began circulating as investors grew concerned over WBD’s debt load and the volatility of its streaming service, Max.
- Spring 2024: Formal discussions commenced, with David Zaslav positioning WBD as a lean, efficient asset. During this period, WBD accelerated its efforts to optimize its content library, resulting in significant cost-saving write-downs.
- Summer 2024: The deal gained momentum as Skydance, backed by the Ellison family, secured the necessary financing to present an all-cash and stock offer that shareholders eventually deemed superior to competing bids.
- September 2024: Regulatory bodies, including the Federal Trade Commission and the Department of Justice, cleared the path for the merger, signaling that the move would not constitute an insurmountable antitrust violation.
- October 6, 2024: The deal officially closed. The $31 per share offer, coupled with the ticking fee for shareholders, finalized the transfer of ownership, effectively dissolving Warner Bros. Discovery as an independent public entity.
The Broader Windfall: Beyond the C-Suite
While Zaslav’s payout has drawn significant attention, he was not the sole beneficiary of the Skydance acquisition. SEC filings released in the wake of the closure indicate that several other top-tier executives at WBD also received nine-figure exit packages.
Zaslav has previously defended his compensation philosophy, asserting that the expansion of equity ownership among the rank-and-file staff was a central pillar of his management strategy. During his tenure, the number of WBD employees participating in equity-based compensation programs more than doubled. Proponents of this approach argue that by extending stock ownership to a broader base of employees, the gains from the Skydance acquisition were more equitably distributed throughout the organization than in previous mega-mergers, where wealth was almost exclusively concentrated at the executive level.
Organizational Restructuring and Executive Departures
The completion of the merger has triggered a seismic shift in the organizational charts of both Skydance and the legacy WBD brands. The integration process, which is expected to take several months, involves a significant reshuffling of personnel.
Some of Zaslav’s most prominent deputies, including Casey Bloys, JB Perrette, and Channing Dungey, have opted to remain with the newly merged entity. Their transition suggests a desire for continuity in high-level operations, particularly within the content production and streaming divisions. Conversely, a distinct group of executives, including Gunnar Weidenfels, Mike De Luca, and Pamela Abdy, have exited the company alongside Zaslav. The departure of these figures marks the end of an era for the studio, as Skydance moves to install its own leadership team to oversee the newly integrated portfolio of assets.
Market Implications and Future Outlook
The $111 billion acquisition serves as a case study for the current state of the media sector. By merging with Skydance, the assets formerly under the WBD umbrella are now part of a more diversified, capital-rich conglomerate. Financial analysts suggest that the primary implication of this merger is the creation of a "scaled-up" media giant better equipped to negotiate licensing deals, invest in high-budget film production, and weather the ongoing turbulence of the advertising market.
However, the size of the executive payouts has reignited broader discussions regarding corporate governance and the "golden parachute" phenomenon. Critics of the merger often point to the disparity between executive wealth creation and the operational challenges faced by the business, such as the decline in linear cable subscribers. Despite these concerns, shareholders largely approved the transaction, viewing the $31 per share payout as a fair valuation in an increasingly difficult economic climate for media conglomerates.
As the dust settles, the industry is left to evaluate whether this massive consolidation will lead to improved profitability or if it will face the same structural headwinds that plagued WBD. For David Zaslav, the transaction represents the conclusion of a high-stakes tenure. His departure, underscored by his massive financial gain, serves as a defining moment in the history of the modern media industry—a period characterized by the dissolution of legacy powerhouses and the emergence of massive, tech-driven entertainment empires.
The transition to Skydance is not merely a change in ownership; it is a fundamental pivot in business strategy. With the infusion of capital from the deal, the new organization is expected to prioritize content stability and digital expansion. Whether this will yield long-term value for the remaining shareholders and employees remains the subject of intense speculation on Wall Street. For now, the focus remains on the logistical challenges of merging two massive workforces and the immediate financial impact of the largest corporate deal of the year.